
ALDI Leadership: ALDI leads U.S. grocery retail with 2,689 locations nationwide.
Regional Dominance: Publix demonstrates strong regional dominance across Florida's grocery market.
Broad Coverage: Trader Joe's maintains broad coverage across 43 states.
Data Intelligence: Scraped location data strengthens grocery competitive market intelligence.
Pricing Insights: Integrated pricing data enables smarter grocery competitive analysis.

The U.S. grocery sector is undergoing a major transformation as retailers expand store networks, optimize pricing, strengthen omnichannel operations, and compete for increasingly price-sensitive consumers. In this environment, Web Scraping 10 Largest Grocery Chains in United States 2026 provides a data-driven view of the country's leading grocery retailers based on store presence, geographic coverage, and competitive footprint.
The benchmark below uses the supplied 2026 location dataset and focuses on ten major grocery chains: ALDI, ALDI Curbside, Albertsons Companies, Publix, Kroger, Food Lion, Safeway Inc., Trader Joe's, Save A Lot, and IGA.
For businesses looking to Scrape US Grocery Chain Data, location-level information can reveal where competitors operate, how densely they are distributed, which markets are saturated, and where expansion opportunities may exist.
The supplied dataset ranks ALDI as the leading grocery chain by location count, with 2,689 locations, followed closely by ALDI Curbside with 2,616 locations and Albertsons Companies with 2,274.
Together, these three entries represent a substantial portion of the location footprint among the top ten chains. The dataset also highlights the significant geographic reach of Trader Joe's and IGA, despite their smaller absolute store counts.
| Rank | Grocery Chain | Locations | States/Territories | Cities | Approx. Share of Top 10 Locations |
|---|---|---|---|---|---|
| 1 | ALDI | 2,689 | 41 | 1,756 | 18.1% |
| 2 | ALDI Curbside | 2,616 | 40 | 1,731 | 17.6% |
| 3 | Albertsons Companies | 2,274 | 36 | 1,218 | 15.3% |
| 4 | Publix | 1,495 | 8 | 536 | 10.1% |
| 5 | Kroger | 1,249 | 16 | 591 | 8.4% |
| 6 | Food Lion | 1,113 | 10 | 577 | 7.5% |
| 7 | Safeway Inc. | 913 | 18 | 520 | 6.1% |
| 8 | Trader Joe's | 661 | 43 | 495 | 4.5% |
| 9 | Save A Lot | 642 | 29 | 488 | 4.3% |
| 10 | IGA | 593 | 34 | 522 | 4.0% |
| Total | Top 10 | 14,845 | --- | --- | 100% |
Location counts reflect the supplied dataset; individual retailer counts may vary by collection date.
This distribution demonstrates why store-level data is increasingly important for understanding the biggest grocery chains in the United States. A retailer with fewer stores can still have extensive geographic coverage, while another may concentrate thousands of locations within fewer states.
ALDI ranks first in the supplied dataset with 2,689 locations across 41 states and territories and approximately 1,756 cities. Its footprint illustrates the retailer's broad national presence and particularly strong penetration in several high-density markets.
The supplied research identifies Florida as ALDI's largest state market, with approximately 319 locations. That represents around 12% of its U.S. store footprint.
For analysts, ALDI's footprint provides an important benchmark for discount grocery expansion. Mapping store locations against competitors can identify overlapping trade areas, underserved ZIP codes, metropolitan concentration, and potential whitespace.
ALDI Curbside appears separately in the supplied dataset with 2,616 locations across 40 states and territories and approximately 1,731 cities.
From a competitive intelligence perspective, digital fulfillment coverage is becoming almost as important as physical stores. A retailer may have a large brick-and-mortar footprint while also competing through pickup and delivery channels.
This creates demand for Grocery Store Location Data Extraction that combines physical addresses with digital service availability, store hours, fulfillment options, delivery coverage, and geographic coordinates.
Albertsons Companies ranks third with 2,274 locations across 36 states and territories and approximately 1,218 cities.
California is identified in the supplied dataset as its largest state market, with approximately 581 locations, accounting for roughly 26% of its reported footprint.
Such concentration creates opportunities for regional competitive analysis. Brands can compare Albertsons locations against nearby Safeway, Kroger, Publix, ALDI, independent supermarkets, and other grocery formats.
This is particularly useful for US grocery competitive market intelligence, where geographic relationships often reveal more than national store totals.
Publix ranks fourth with approximately 1,495 locations in the main ranking. The supplied detailed section reports 1,498 stores, demonstrating why collection dates and data-refresh cycles must be considered when constructing grocery datasets.
Florida dominates the Publix footprint, with approximately 919 locations according to the supplied research, representing about 61% of the reported total.
This concentration provides an excellent example of how national rankings can hide highly regional competitive dynamics. Publix has fewer states represented than some competitors but maintains substantial store density in its core markets.
Kroger ranks fifth with 1,249 locations in the ranking, while the detailed supplied data reports 1,250 stores.
Ohio is identified as Kroger's leading state market, with approximately 202 locations. This represents around 16% of the reported footprint.
For grocery analysts, Kroger's store distribution can be evaluated alongside local pricing, promotions, product assortment, loyalty programs, delivery availability, and competitor proximity.
Food Lion occupies sixth position with 1,113 locations across 10 states and territories and approximately 577 cities.
North Carolina is its dominant market, accounting for approximately 507 stores, or nearly 46% of its footprint according to the supplied figures.
This level of concentration makes Food Lion particularly relevant for state-level and city-level grocery competition studies. Analysts can monitor how its locations overlap with Publix, ALDI, Kroger, and other regional operators.
Safeway Inc. ranks seventh with 913 locations in the primary table, while the detailed dataset reports 911 stores.
California contains approximately 243 Safeway locations, representing about 27% of its reported footprint.
The difference between ranking and detailed counts demonstrates a fundamental challenge in grocery data collection: Grocery Chain Competitive Data Analysis requires timestamped datasets because locations open, close, relocate, rebrand, and change operating formats continuously.
Trader Joe's has 661 locations according to the supplied ranking and is present across 43 states and territories, giving it one of the broadest state-level footprints among the listed retailers.
California contains approximately 211 Trader Joe's locations, or around 32% of its reported U.S. network.
Its footprint shows that store count alone does not fully measure competitive strength. Geographic breadth, local density, customer demographics, product positioning, and market overlap all contribute to competitive analysis.
Save A Lot ranks ninth with 642 locations in the main table, while the detailed data reports 619 stores. Ohio is its strongest identified state market, with approximately 97 locations.
IGA ranks tenth with 593 stores across 34 states and territories and approximately 522 cities. North Carolina is identified as its largest state market, with 64 stores.
IGA's large city count relative to its total location count illustrates the importance of examining geographic distribution rather than relying exclusively on store totals.
| Grocery Chain | Reported Locations | Leading State | Leading-State Locations | Approx. State Share | States/Territories | Cities | Geographic Character |
|---|---|---|---|---|---|---|---|
| ALDI | 2,689 | Florida | 319 | 11.9% | 41 | 1,756 | Broad national discount footprint |
| ALDI Curbside | 2,616 | --- | --- | --- | 40 | 1,731 | Broad fulfillment coverage |
| Albertsons Companies | 2,274 | California | 581 | 25.5% | 36 | 1,218 | Strong West Coast concentration |
| Publix | 1,495 | Florida | 919 | 61.5% | 8 | 536 | Highly concentrated Southeast footprint |
| Kroger | 1,249 | Ohio | 202 | 16.2% | 16 | 591 | Strong Midwest/South presence |
| Food Lion | 1,113 | North Carolina | 507 | 45.6% | 10 | 577 | Concentrated Southeast network |
| Safeway Inc. | 913 | California | 243 | 26.6% | 18 | 520 | West-heavy geographic footprint |
| Trader Joe's | 661 | California | 211 | 31.9% | 43 | 495 | Broad states, concentrated core market |
| Save A Lot | 642 | Ohio | 97 | 15.1% | 29 | 488 | Distributed regional network |
| IGA | 593 | North Carolina | 64 | 10.8% | 34 | 522 | Highly distributed market presence |
Percentages are calculated from the supplied figures and rounded.
A basic store directory provides only names and addresses. A comprehensive grocery scraping pipeline can produce a much richer competitive dataset.
Grocery Data Scraping in the USA can capture store names, addresses, ZIP codes, phone numbers, latitude and longitude, opening hours, store status, categories, services, delivery options, pickup availability, and URLs.
When collected consistently, these fields can support location intelligence, market sizing, territory planning, franchise analysis, competitor monitoring, and retail expansion research.
A structured Grocery Data Scraping Services workflow can also normalize data from multiple grocery websites into one standardized dataset. This makes cross-retailer comparisons substantially easier.
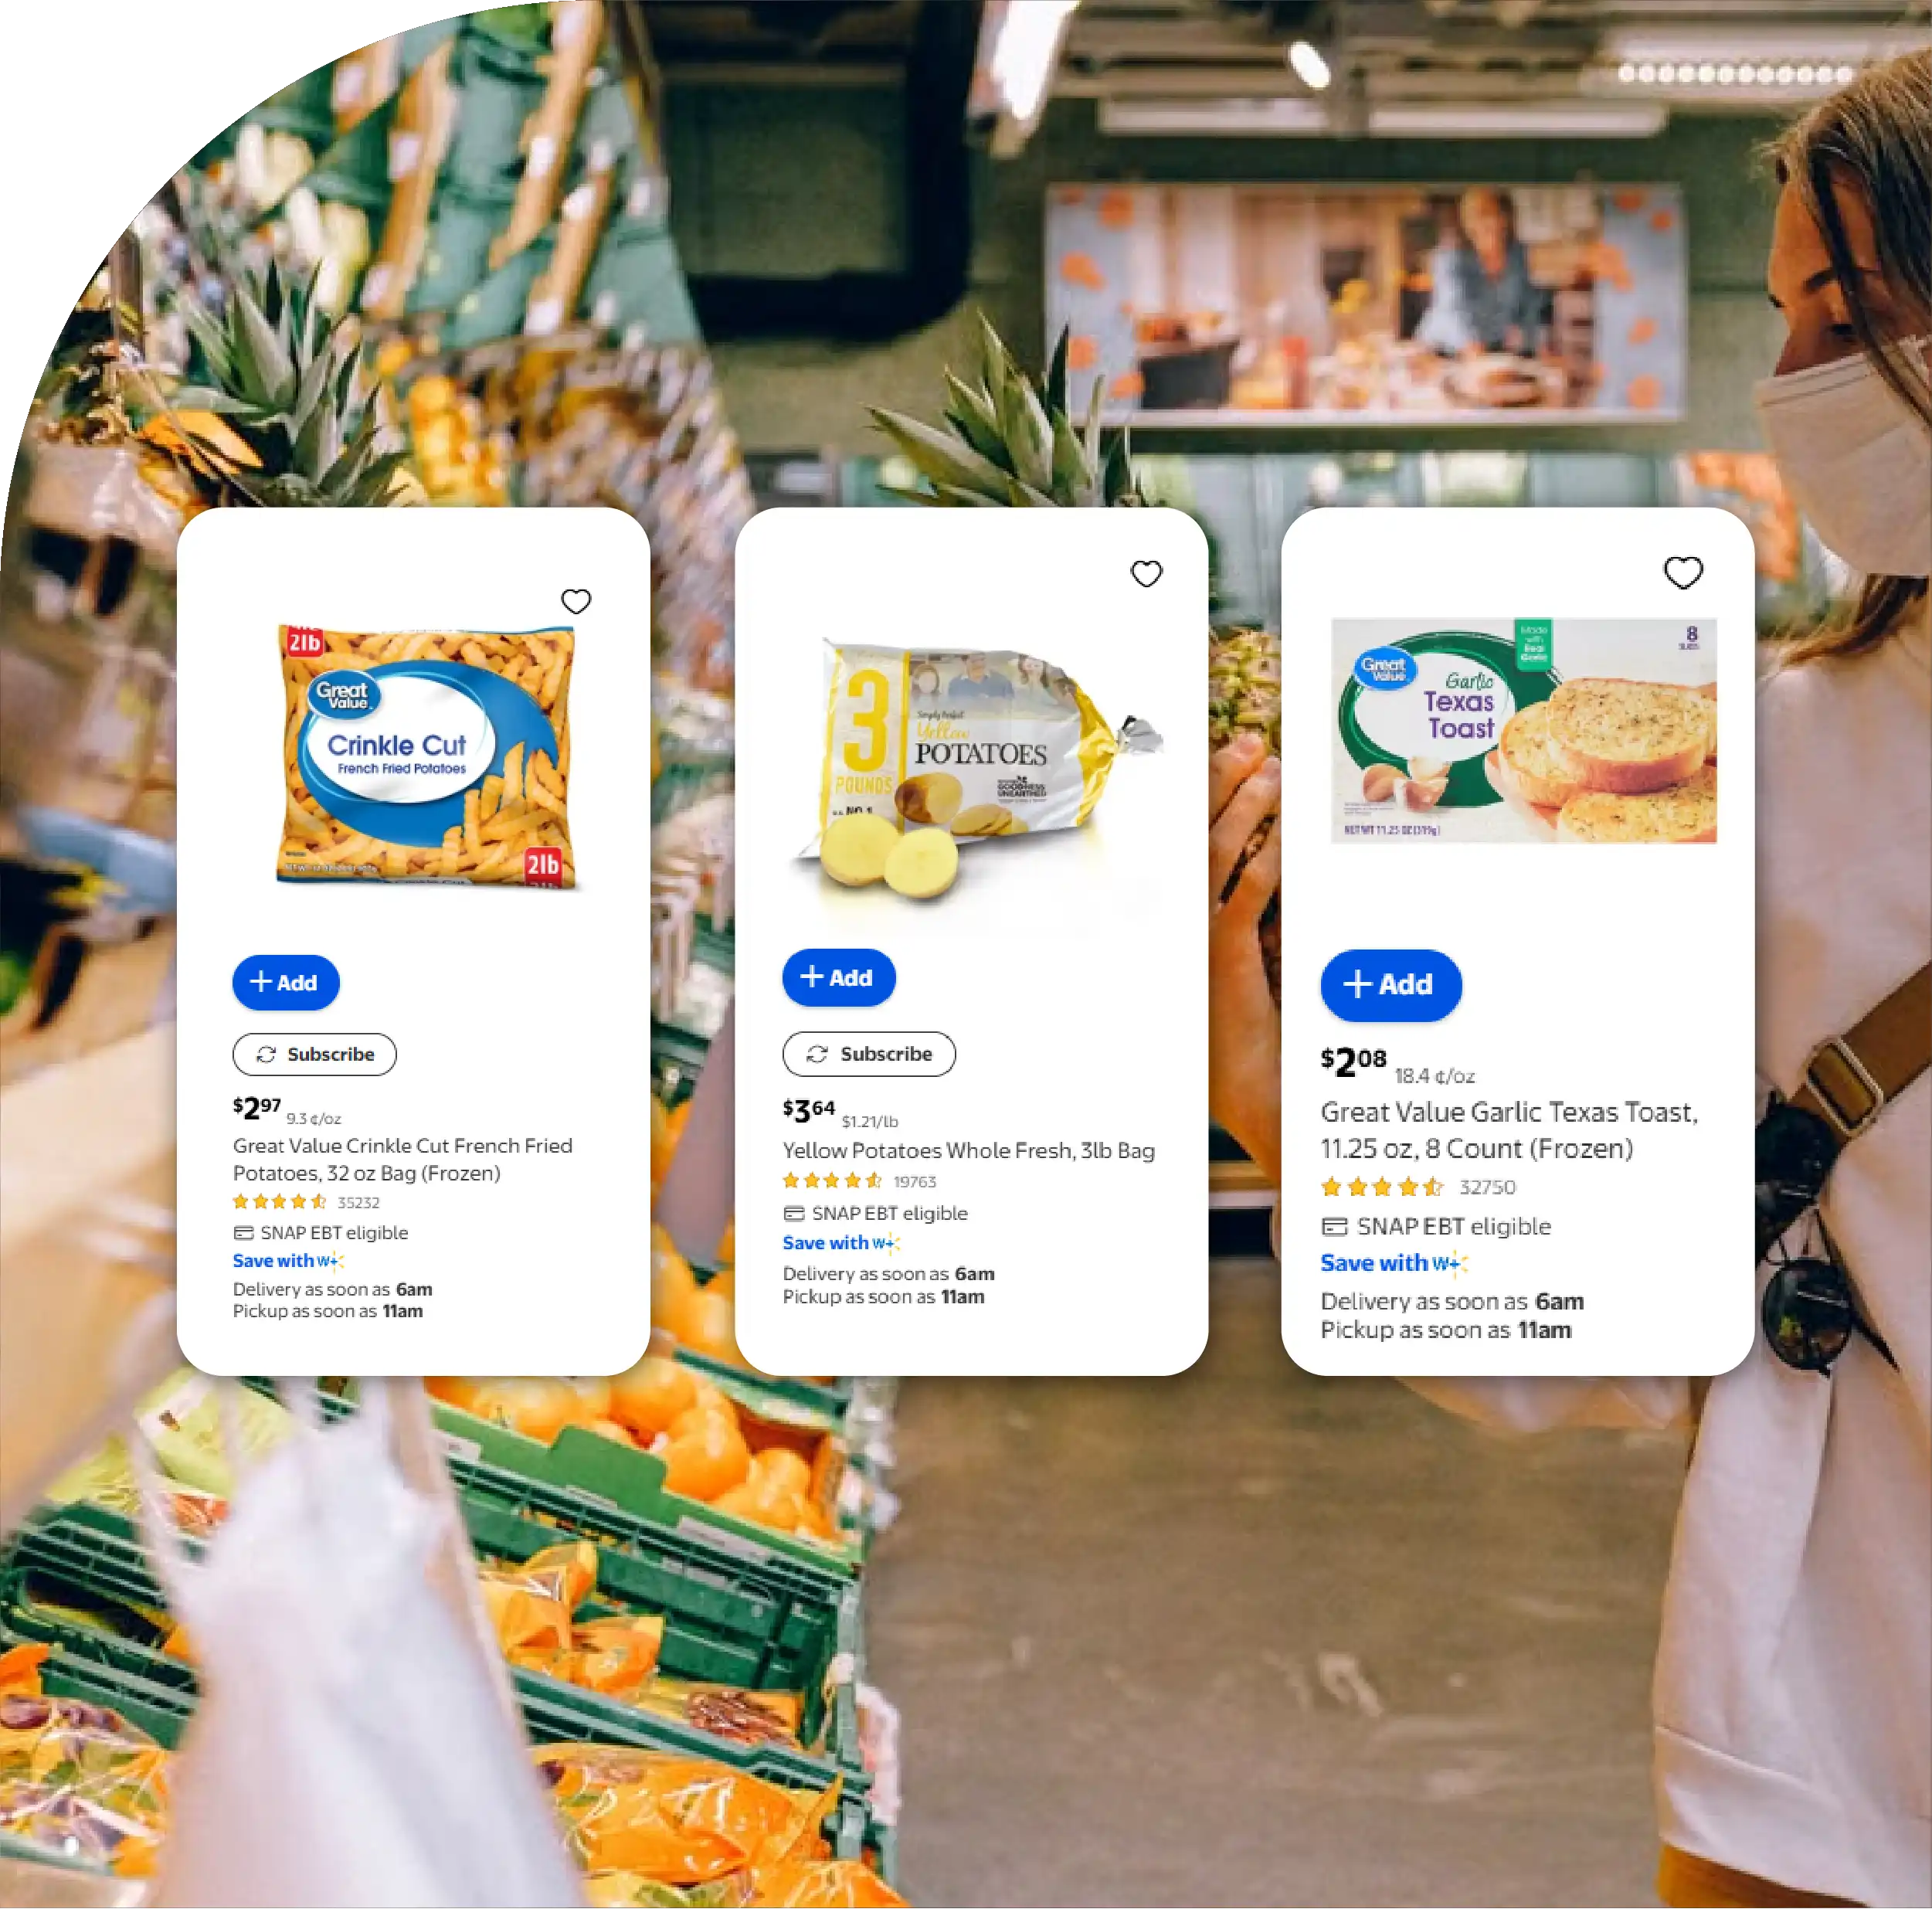
The most valuable datasets go beyond store locations. A modern grocery intelligence system can connect location information with product catalogs, prices, promotions, stock availability, ratings, delivery fees, and estimated fulfillment times.
For example, analysts can create a record containing:
This structure enables retailers to move from static store counting toward continuously updated competitive intelligence.
Physical grocery stores increasingly operate as fulfillment nodes for online orders. Consequently, store-location intelligence should be connected with delivery and pickup information.
Grocery Delivery Scraping API Services can help businesses collect structured delivery information across supported grocery platforms and connect it with store-level datasets.
This allows analysts to compare delivery availability by ZIP code, estimate service-area overlap, identify underserved markets, monitor delivery charges, and understand how physical store expansion affects digital coverage.
The next evolution is using machine learning to transform raw scraped information into actionable insights.
AI Grocery Intelligence can combine historical prices, location changes, product availability, promotions, competitor movements, and consumer demand signals to identify emerging market patterns.
Potential applications include competitor price alerts, store expansion forecasting, assortment recommendations, promotion monitoring, stockout prediction, market-gap identification, and automated competitor benchmarking.
Location data becomes significantly more useful when connected to pricing intelligence.
A Grocery Price Dashboard can bring together retailer prices, discounts, promotions, product availability, store locations, and historical changes in a single analytical environment.
For example, a retailer could compare the same branded product across ALDI, Kroger, Publix, Food Lion, Safeway, and other competitors. Analysts could then measure average price differences, promotional frequency, price volatility, and regional variations.
| Metric | Example Measurement | Business Value |
|---|---|---|
| Total store locations | 14,845 across top 10 | Measures competitive scale |
| State coverage | 8–43 states/territories | Measures geographic reach |
| City coverage | 488–1,756 cities | Measures market penetration |
| Leading-state concentration | 10.8%–61.5% | Identifies regional dependency |
| Store density | Stores per 100,000 residents | Compares market intensity |
| Competitor proximity | Distance in miles | Identifies overlapping trade areas |
| Product price gap | Percentage difference | Supports pricing strategy |
| Promotion frequency | Offers per week | Measures promotional intensity |
| Availability rate | Percentage in stock | Evaluates fulfillment strength |
| Delivery coverage | ZIP codes served | Measures digital reach |
| Price volatility | Weekly/monthly change | Detects dynamic pricing |
| New-store activity | Openings per quarter | Tracks expansion |
The grocery market is not simply a contest over the highest number of stores. Retailers compete through price, convenience, assortment, loyalty programs, delivery speed, promotions, private labels, and geographic accessibility.
A continuously refreshed grocery dataset allows businesses to answer questions such as:
These insights can influence site selection, pricing, merchandising, marketing, assortment planning, and expansion strategies.
The supplied 2026 benchmark places ALDI at the top of the listed U.S. grocery chains by location count, followed by ALDI Curbside and Albertsons Companies. However, the geographic analysis reveals a more complex market: Publix is exceptionally concentrated in Florida, Food Lion in North Carolina, Albertsons and Safeway have significant California exposure, while Trader Joe's combines broad state coverage with a strong California concentration.
For businesses, the real opportunity lies beyond counting stores. Automated web scraping can connect store locations, product prices, promotions, availability, delivery coverage, and competitive movements into one continuously refreshed intelligence layer.
Because the supplied source contains small count differences between its ranking table and detailed retailer sections—for example, ALDI 2,689 vs. 2,687 and Publix 1,495 vs. 1,498—production datasets should always retain a collection timestamp and source snapshot. This is essential when using grocery intelligence for benchmarking, reporting, or automated decision-making.